46-year-old CEO decided to share part of the fortune from the company sale with workers who helped overcome fires, economic crises, and difficult years
🔎 What You Need to Know
- Fibrebond nearly collapsed after a devastating fire in 1998 and the dot-com bubble crisis.
- Some employees initially believed the multimillion-dollar bonus was a joke.
- The company’s 540 workers are expected to receivean average of about US$443,000 each, even without owning shares in the business.
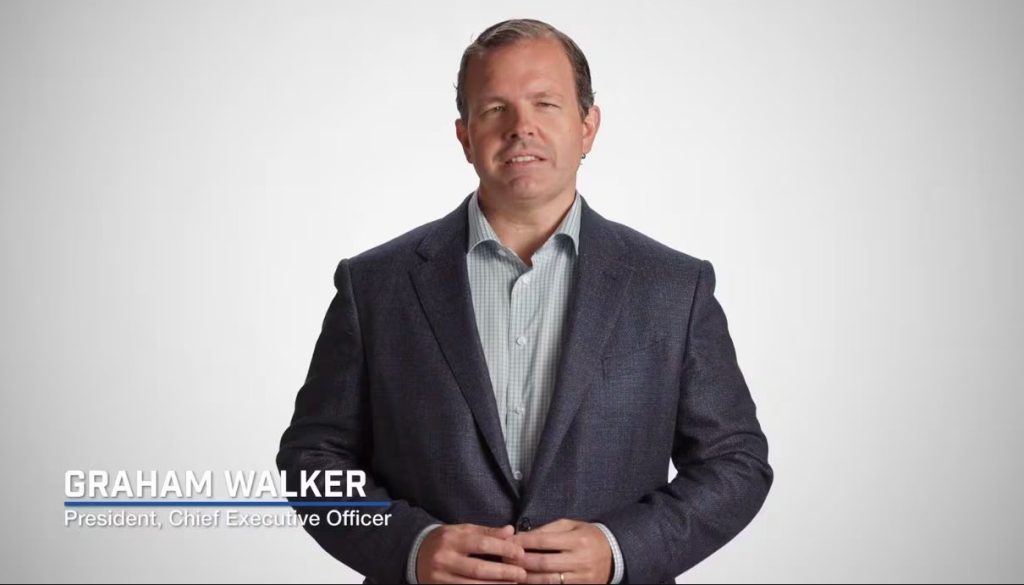
A rare gesture in the corporate world transformed the lives of hundreds of workers in the United States. After selling the family-owned company Fibrebond for US$1.7 billion, businessman Graham Walker, 46, decided to allocate US$240 million in bonuses to the company’s employees.
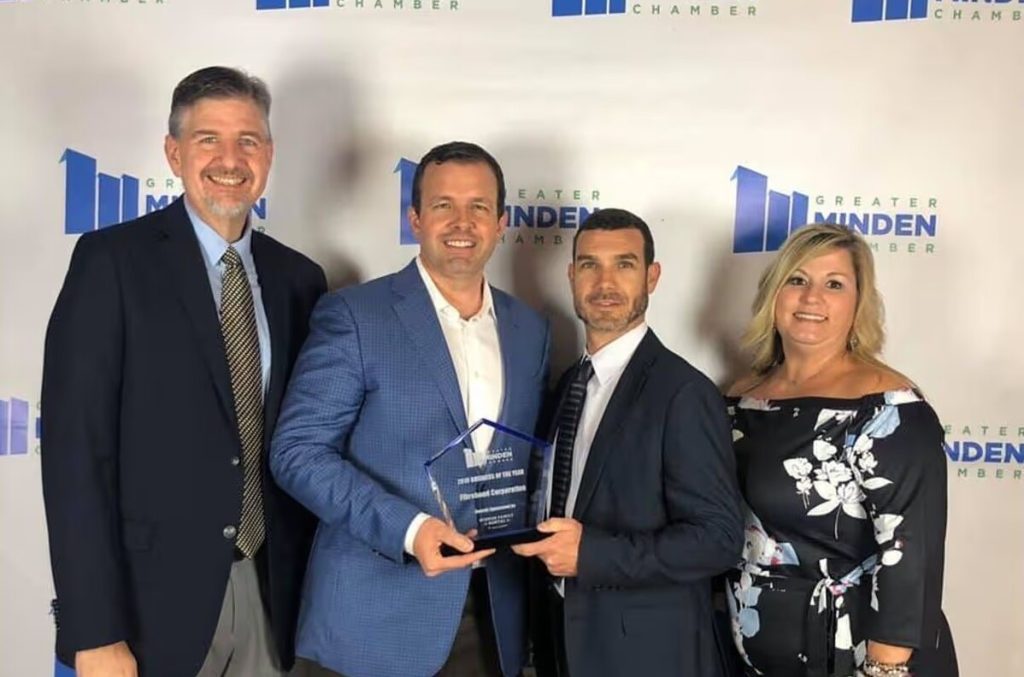
The decision attracted international attention not only because of the enormous amount involved, but also because of the story behind it. Fibrebond, headquartered in the small town of Minden, Louisiana, survived devastating fires, economic crises, and difficult years before becoming one of the companies benefiting from the explosive growth of infrastructure for artificial intelligence and data centers.
According to a report by The Wall Street Journal, Walker required that 15% of the company’s sale value be reserved for Fibrebond’s 540 full-time employees — even though they did not own equity stakes in the business.
The Decision That Shocked Employees
Payments began in June 2025, and on average, each worker is expected to receive around US$443,000 over five years.
The announcement was so unexpected that many employees initially thought it was some kind of prank.
“It was surreal, like telling people they had won the lottery. It was absolute shock,” said Hector Moreno, the Fibrebond executive responsible for distributing the bonuses, according to the newspaper.
Some workers reportedly asked:
“What’s the catch?”
Walker explained that he especially wanted to reward those who stayed loyal to the company during its toughest years.
“I hope I’m 80 years old and get an email telling me how this impacted someone,” the former CEO said.
Company Survived Devastating Fire and Nearly Collapsed
According to the New York Post, Fibrebond was founded in 1982 by Claud Walker, father of Graham Walker. The company manufactures enclosures and infrastructure for electrical equipment and is described as a leader in wireless communication solutions.
Over the decades, however, the company faced serious difficulties.
In 1998, a devastating fire struck the factory. Shortly afterward, the collapse of the dot-com bubble drastically reduced demand for the company’s services.
Its workforce fell from approximately 900 employees to just 320.
Even during the crisis, the Walker family continued paying workers’ salaries throughout the hardest periods, helping create strong internal loyalty.
Walker later said the nearly quarter-billion-dollar payout was his way of thanking employees who remained with the company through:
- the 1998 fire;
- mass layoffs;
- years of wage freezes;
- and financial struggles before the recent growth surge.
The US$150 Million Bet That Changed Everything
According to The Wall Street Journal, Fibrebond’s major turning point came in 2020.
That year, the company invested around US$150 million in building infrastructure for data centers, including enclosures for power equipment.
The gamble proved extremely profitable during the global artificial intelligence boom.
Over the past five years, Fibrebond’s sales grew approximately 400%, attracting the interest of major corporate groups looking to acquire the company.
It was in this context that Eaton, an intelligent power management company, completed the $1.7 billion acquisition of Fibrebond.
Employees Paid Off Debts, Opened Businesses, and Retired
The bonuses quickly transformed the lives of many workers.
Lesia Key, a longtime Fibrebond employee, told the newspaper she started working at the company in 1995 earning just US$5.35 per hour.
With the multimillion-dollar bonus, she was able to pay off her mortgage and open a clothing boutique.
“Before, we lived paycheck to paycheck. Now I can live comfortably; I’m grateful,” she said.
Another veteran employee, Hong Blackwell, retired at age 67 and bought a new Toyota Tacoma for her husband.
According to reports, other employees used the money to:
- pay off credit card debt;
- cover college expenses;
- increase retirement savings;
- or help family members.
Bonus Payments Came With a Condition
Despite the excitement, the agreement included an important condition.
The bonuses were not paid in full all at once. To receive the entire amount, employees must remain with the company for five years after the sale.
Walker explained that he made the decision to avoid an immediate employee exodus following the announcement.
“I don’t think we would have had many employees on day two,” he told The Wall Street Journal.
According to him, the measure would help ensure a stable transition to Eaton and protect the local economy of Minden, a Louisiana town with about 12,000 residents.
Still, Walker created one important exception: workers over the age of 65 were exempt from the requirement and allowed to retire immediately without losing the benefit.
“More Than 10%,” CEO Responded
When asked why he chose exactly 15% of the sale value for employees, Walker gave a simple answer:
“It’s more than 10%.”
The phrase eventually became one of the defining symbols of the case’s widespread attention.
When Graham Walker officially stepped down as CEO on December 31, 2025, he and his family still earned more than US$1 billion from the company sale.
Even so, the businessman said he believed sharing nearly a quarter of a billion dollars with employees was the right decision.
“Almost a quarter of a billion dollars in employees’ hands felt fair,” he declared.
Sources: The Wall Street Journal and the New York Post
Read more:
WSJ: Click here
NY Post: Click here